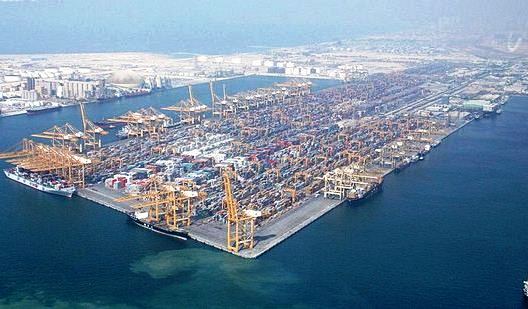
 After years of healthy growth, many terminal operators are entering 2017 facing a challenging future, their operations undermined by pressure from carriers to lower handling costs and by rising expenses, said a new report from a global shipping consultancy.
“Terminal operators face a ‘perfect storm’ of rising costs due to bigger ships, greater business risks from larger liner alliances, softening global demand growth, and pressure on terminal handling prices from cash-strapped carriers,” according to the recently launched “Ports and Terminals Insight” of Drewry.
The financial results of listed port and terminal operators reveal a weakness in organic earnings amid escalating debt levels, underlining the cautious assessment of growth in the sector, said Drewry. Its Port Index, a market weighted assessment of share price performance of the top listed operators, slumped 10% in the last quarter.
Resisting downward pressure on terminal handling prices will be challenging but not impossible, as much depends on local market conditions and the extent of choice for ever larger ships and alliances, added the insight.
The report said port operators should apply stricter cost rationalization and financial risk reduction in order to retain investment interest. Those that can develop growth plans will be able to command a significant market premium amid diminishing profitability.
In a stark warning to container shipping lines, Drewry’s senior analyst for ports and terminals Neil Davidson said: “Shipping lines need to be careful how they play the situation. If the returns from investing in and operating terminals fall too far, or the risks become too high (or both), then terminal operators may simply stop investing.”
However, there are some active steps that terminal operators can take to find their way through the storm. According to the new report, they can focus on organic growth hotspots such as South Asia and the Middle East, or they can buy market share through acquisitions.
“South Asia is set to be a star performer in relative terms, with its manufacturing industry likely to take some of the activity previously carried out in China. And in the Middle East, major infrastructure projects are expected to resume after a hiatus caused by the low oil price,” said the study.
Buying market share through acquisitions in an attempt to outperform market growth is a strategy already being pursued by several port groups including Cosco Shipping Ports, China Merchants Port Holdings and Yildirim Group (Yilport Holdings), all of which have made recent high-profile acquisitions.
Photo: Imre Solt