The specialist reefer industry is expected to end strong in 2011, but increasing competition from the containerized sector could force it to contract and move into niche shipping in the next few years, a global maritime consulting company predicts in its latest report, “Reefer Shipping Market Annual Review and Forecast 2011/12.”
“As the burgeoning containerized reefer market continues unabated, the specialist reefer fleet is feeling the strain,” Drewry Maritime Research said in a news release dated September 13, 2011. “With twelve-month charter rates forecasted to continue sliding, scrapping levels gaining pace and for the first time an empty newbuild orderbook, the industry is changing quickly.”
Overall year-end forecast rates for the spot market in 2011 will remain above 2010, but charter rates will continue to fall this year after losing 10 percent in 2010, Drewry noted. And with containership operators posing a strong competition, “the financial outlook is a cautious one,” it added.
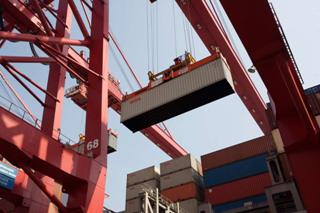
Worldwide trade in perishable products, along with seaborne trade, has been on an upward trend in 2010, boosting demand for reefer capacity, Drewry said. But the mode of transport “continues to change the industry, with forecasts indicating that by 2014 some 74 percent of perishable reefer cargo will be carried by containerships—that will provide up to 95 percent of overall reefer capacity.”
In addition, the newbuild orderbook now stands at zero, and strong scrapping programs have removed 36 vessels a year on average between 2008 and 2010. With a further 19 added to the list as of June 2011, the fleet now stood at 691 vessels. Drewry said that at this rate, the fleet could be cut down to 476 vessels by 2015.
These developments will likely steer the specialized reefer fleet along the route of niche shipping, it said. “Many trades are ideally suited to specialized reefer services and it is these that will ensure its continuing—and profitable—future, albeit on a smaller scale than in previous years.”
The containerized sector benefits from this trend, but it is by no means gifted an untroubled future, said Drewry’s Susan Oatway, who added that reefer pricing could be an issue.
“On the one hand they will be keen to see constant—or increasing—utilization levels of reefer slots. Given the high number of newbuildings scheduled to deliver, this suggests downward rate pressure.
“On the other hand, they will be keen to maintain pricing structures given both the impact this inevitably has on other cargoes, as well as their current financial concerns,” she said.
Photo by rais58